Común: Your money, your way

Screenshots
Details
- Rating
- 2.75K reviews
- Version
- 2.29.0
- Developer
- Comun
Analysis by Norviv
Managing money becomes more complicated when it is shared across a household, split between relatives, or sent regularly to family in another country. I found Común most interesting in that space: it is a free finance app from Comun that combines person-to-person payments, transfers to Latin America, and a Visa debit card in one place. That combination makes it more than a basic spending tracker, although it is not automatically the best replacement for every bank account or payment service.
My overall impression is that Común is easiest to appreciate when you have a clear reason to move money between people. It can fit a household where one person pays for something and another needs to reimburse them, or where someone wants a straightforward way to send money to relatives in Latin America. The app is rated 4.8 from around 22 thousand ratings, with over 500 thousand installs, so it has clearly attracted a substantial audience. Still, a high rating does not remove the need to think about account access, trust, transfer timing, and how the debit card fits into your existing financial routine.
How Común works in a shared household
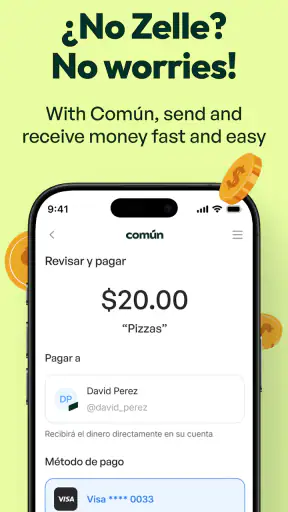
A realistic example is a household in which one adult handles a grocery purchase while another contributes later. Instead of passing around cash or manually calculating who owes what, the person who paid can use Común to request or receive money. The same basic idea applies to rent contributions, shared meals, school supplies, or a recurring family expense. I like this use because it keeps the action focused: send money, receive money, or use the card, rather than forcing every household member to adopt a complicated budgeting system.
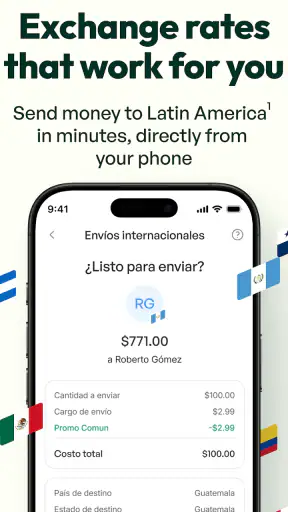
The app can also make sense for families with relatives in Latin America. A user may need to send money internationally without opening a separate service each time, while still keeping everyday payments and card spending nearby. That convenience is the central appeal. Instead of treating domestic transfers, international support, and card use as unrelated tasks, Común presents them as parts of one money routine.
There is an important distinction, though. Común helps people move and use money; it should not be mistaken for a shared household ledger unless your own workflow supplies that organization. Before sending anything, I would decide whether the household needs a simple payment tool or a complete record of bills, categories, balances, and reimbursements. If detailed financial reporting is your priority, a traditional banking app or dedicated budgeting tool may remain more suitable.
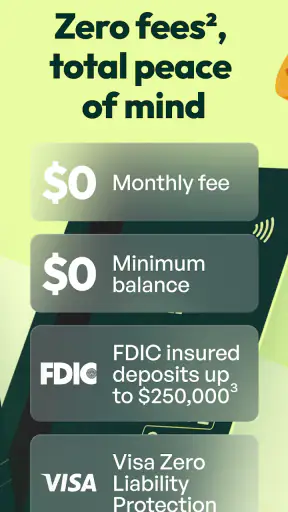
The Visa debit card adds another practical layer. It can be useful for giving the account a physical spending role rather than limiting it to transfers inside the app. In my view, the card is most helpful when you want a separate way to spend money that has been placed in Común. I would still avoid treating it as the only payment method until I had tested the parts of the service that matter most to my routine, such as receiving money, using the card, and sending an international transfer.
Start with clear account boundaries
Shared use works best when every person understands whose account it is and who is responsible for each transaction. I would not casually share one login across a household. Even when the goal is convenience, combining identities can make it difficult to tell who initiated a payment, who should receive a refund, or who is responsible for a card purchase. A cleaner arrangement is for each person to use their own account where appropriate and coordinate payments openly.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
This matters especially when a phone is used by more than one person. A shared device can make an app feel like a shared account, but those are not the same thing. I would sign out when necessary, avoid leaving financial screens visible, and make sure the person sending money can review the recipient before confirming. These are simple habits, but they reduce the chance of an accidental transfer or an argument over who approved a purchase.
Común is free to download and use, which lowers the barrier to trying it. That does not mean every financial action should be treated casually. Before relying on it for an important household payment, I would first make a small, ordinary transfer to understand the flow and confirm that everyone involved is comfortable with the steps. The best test is not reading a feature list; it is seeing whether the app fits the way your household actually communicates about money.
The app is intended for Everyone, but an age label should not be confused with independent financial readiness. A younger person may be able to understand the interface while still needing an adult to explain spending limits, transfers, and the consequences of sharing access. For a household, the practical boundary is responsibility: who owns the money, who controls the account, and who checks a transaction before it is sent.
Coordinate payments without creating confusion
One useful habit is to agree on a short description for every household payment. A note such as “electric bill,” “market,” or “family transfer” is more valuable than a vague message because it gives everyone a shared reference later. I would also separate urgent payments from routine reimbursements. Sending money to a relative abroad and splitting a restaurant bill may both happen in Común, but they deserve different expectations about timing and confirmation.
For recurring household expenses, I would keep a simple external reminder even if Común handles the payment itself. The app can be the action point, but a calendar or written household plan can remain the place where people remember due dates and responsibilities. This avoids a common mistake: assuming that a payment app automatically becomes a complete household management system.
International transfers deserve extra care. Before sending money to Latin America, I would confirm the recipient’s details, the destination, the amount, and the expected arrival process. I would also avoid making a last-minute transfer the first test of the service. A small planned transaction is a better way to learn how the workflow feels than waiting until a relative needs money urgently.
Another practical tip is to keep domestic and international purposes mentally separate. If the same balance is used for groceries, personal spending, and family support abroad, it can become difficult to know what remains available. I would decide whether Común is primarily a transfer account, a spending account through the Visa card, or both. That decision makes the app easier to manage and helps prevent accidental overspending.
Trust, age, and shared-device habits
Financial apps need a higher level of trust than ordinary social or shopping apps. In a family setting, that trust should be discussed rather than assumed. A parent might help a teenager understand how to use a debit card, while an adult sibling might coordinate an international transfer with another relative. In each case, the people involved should know what they are agreeing to and should not rely on a shared phone as proof that everyone has permission.
I would be especially careful when several people use the same device. Notifications, saved sessions, and visible balances can reveal private information even when nobody intends to access another person’s account. The safest household arrangement is one where each user knows when the device is available, protects their own access, and checks the recipient and amount before completing a transaction.
Común may be a good introduction to digital money for someone who wants a focused way to send, receive, and spend. It is less convincing as a teaching tool for broader financial planning because those lessons require conversations about saving, recurring obligations, emergency funds, and responsible borrowing. I would use the app as one part of that education, not as a substitute for it.
Trust also affects international support. When sending money to relatives, I would agree in advance on who confirms receipt and how the household records the transfer. That small step prevents repeated payments and makes it easier to distinguish a delayed confirmation from a failed transaction. The app can facilitate the movement of money, but the family still needs a communication habit around it.
Where it fits beside banks and other payment apps
Compared with a conventional bank app, Común feels more focused on direct payments, international family support, and card-based access. A bank may be the better home for salary deposits, long-term savings, loans, statements, and a broad range of financial products. I would not move every part of my financial life into Común simply because it combines several convenient functions.
Compared with a general peer-to-peer payment app, its Latin America transfer option and Visa debit card give it a more specific identity. That can be an advantage if those are the exact tasks you need. If you only split occasional meals with friends, a familiar local payment tool may be faster simply because everyone already uses it. The right choice depends less on which app has the most functions and more on where your recipients and spending habits already are.
For a household, the strongest reason to choose Común is consolidation. One app can sit near the center of a routine involving person-to-person payments, transfers to Latin America, and card spending. The trade-off is that consolidation can make the account more important, so I would pay closer attention to access habits and transaction review than I would with a casual payment app.
The current version is 2.29.0 and requires at least OS 10. That makes device compatibility a basic checkpoint before a household adopts it. If one family member uses an older phone that cannot run the app, the household may need a different coordination method for that person. I would check every intended user’s device before making Común the shared payment plan.
Who should use it and who should skip it
I would recommend Común to someone who regularly sends money to Latin America, wants a Visa debit card connected to that routine, or needs a straightforward way to pay other people from a finance app. It also makes sense for a household that can agree on clear account boundaries and does not expect the app to replace a full budgeting system.
I would be more cautious if your main goal is detailed expense analysis, joint financial planning, or managing many products from one established bank. In those situations, your bank’s app or a dedicated budgeting service may offer a better overall structure. I would also skip it as a household solution if everyone plans to share one login or one device without clear rules. The convenience would not justify the confusion that could follow.
People who send money internationally only once in a while should compare the complete experience with their existing option, including how familiar the recipient is with receiving funds. A service can be technically convenient but still awkward if the other person does not know what to expect. Común is most compelling when its transfer and card features match a repeated, understandable need rather than a single emergency.
My household verdict
After looking at Común as a household finance tool, I see a practical app with a clear purpose rather than an all-in-one answer to every money problem. Its combination of payments, transfers to Latin America, and a Visa debit card can simplify a family routine, especially when people need to move money between one another or support relatives abroad.
My advice is to begin with one defined use case. Try it for reimbursements, planned family transfers, or card spending, then decide whether it deserves a larger role. Keep account ownership separate, review every recipient and amount, and use a simple household note or calendar for obligations the app does not organize for you. Those habits make the experience more dependable than treating the app as a shared wallet.
Comun has developed an app that feels most valuable when convenience and coordination meet. It is free, accessible to an Everyone audience, and well regarded by its users, but the real question is whether its particular mix of features matches your household. For families that need practical money movement without pretending that one app solves every financial task, Común is worth trying.
Frequently Asked Questions
01What is Común: Your money, your way?
Común: Your money, your way is a personal finance app designed to help users manage everyday money more conveniently. It brings financial tools into one place, allowing you to review your activity, organize your finances, and keep better track of spending. The exact services available may depend on your country, eligibility, and the account or products offered through the app.
02Is Común: Your money, your way safe to use?
The app is built for handling sensitive financial information, so security and privacy are important parts of the experience. Before signing up, users should review the permissions requested, privacy policy, account terms, and available security controls. As with any financial application, use a strong, unique password, enable extra verification when available, and avoid accessing your account on unsecured public networks.
03What can I do with Común: Your money, your way?
The features available in Común may include viewing account information, monitoring transactions, managing money, and accessing financial services provided through the platform. Depending on your location and account type, some options may differ or require verification. It is worth checking the current app listing and official terms before downloading, especially if you are looking for specific tools such as transfers, payments, budgeting, or cards.
04Is Común: Your money, your way free to download and use?
Downloading a finance app is often free, but that does not necessarily mean every service is without cost. Común may apply fees, limits, eligibility requirements, or different pricing depending on the financial product and your location. Before using any paid feature, carefully check the fee schedule, exchange rates, transfer conditions, and account terms shown in the app or on the provider’s official website.
05Who can use Común: Your money, your way, and what is needed to register?
Availability may depend on the country where you live, your age, and whether you meet the provider’s eligibility requirements. Registration for a financial service commonly involves providing personal details, confirming a phone number or email address, and completing identity verification. Have accurate information and valid documents ready, and remember that approval is not guaranteed until the provider completes its checks.


